Key takeaways
- check_circleWhat it estimates: Principal and interest from the loan amount, rate and term; add tax, insurance and PMI for a fuller budget.
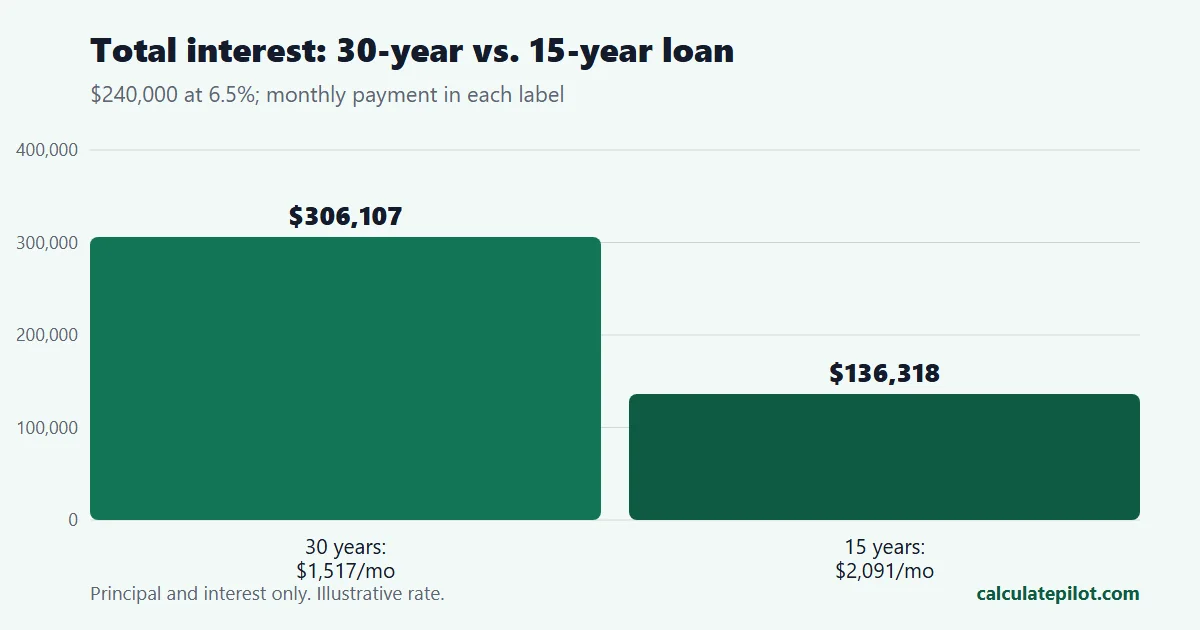
- check_circleTerm trade-off: A 15-year loan has a higher monthly payment but can cost substantially less interest than a 30-year loan.
- check_circleEstimate, not a quote: Actual offers depend on lender pricing, credit, fees, taxes and insurance.
1. What a mortgage calculator helps you estimate
A mortgage calculator turns a few loan assumptions into a useful planning estimate. Enter the home price or loan amount, down payment, interest rate, and loan term to see an estimated monthly principal-and-interest payment. Many calculators also let you add property tax, homeowners insurance, homeowners association dues, and private mortgage insurance so the result reflects a more realistic housing budget.
The key word is estimate. A calculator is excellent for comparing scenarios before you speak with a lender, but it is not a loan approval or a binding quote. Your actual payment can change because of lender fees, discount points, credit profile, local taxes, insurance premiums, escrow rules, and the exact date your loan closes.
2. The mortgage payment formula
For a standard fixed-rate loan, the principal-and-interest payment is based on the loan amount, the monthly interest rate, and the number of monthly payments.
To use an annual interest rate in the formula, divide it by 12 and convert the percentage to a decimal. For example, 6.5% per year becomes 0.065 ÷ 12. A 30-year mortgage has 360 monthly payments, while a 15-year mortgage has 180.
3. Try a mortgage payment yourself
Change the loan below and watch the payment update. Principal and interest only.
4. Worked example: how the numbers fit together
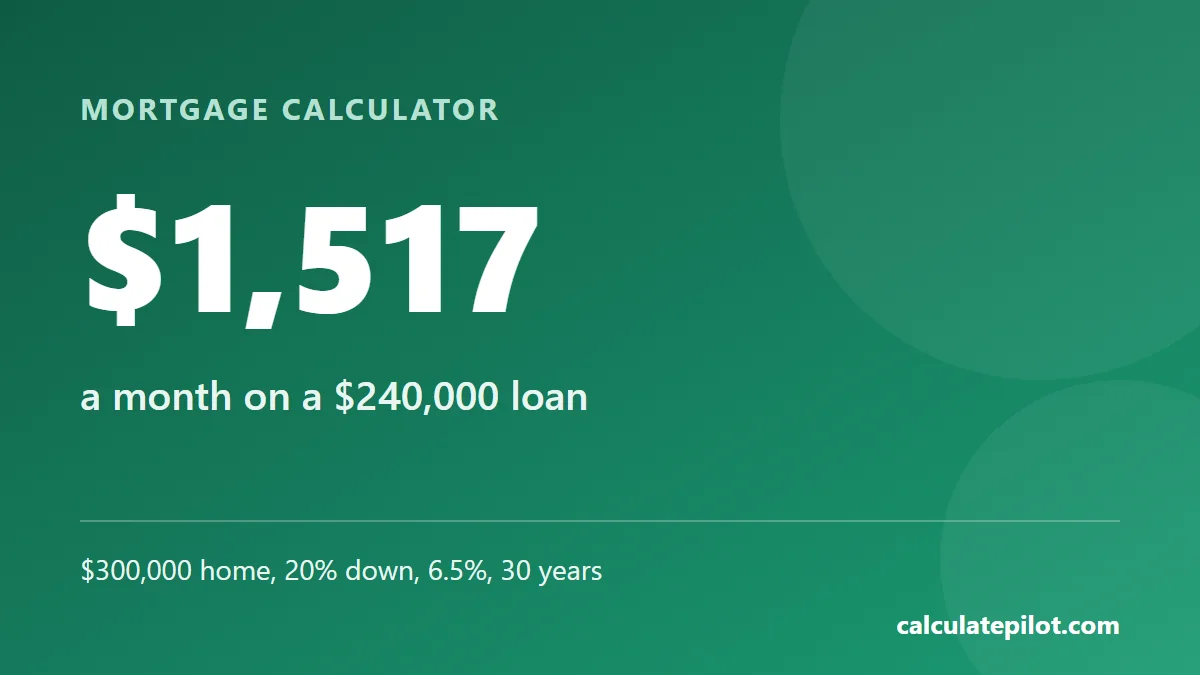
Suppose a home costs $300,000 and you make a 20% down payment. The loan amount is $240,000. If the fixed interest rate is 6.5% and the term is 30 years, the calculator estimates the principal-and-interest payment using 0.065 ÷ 12 as the monthly rate and 360 as the number of payments.
The down payment reduces the amount borrowed, which reduces both the monthly payment and the total interest. In this example, the 20% down payment may also help you avoid private mortgage insurance, depending on the lender and loan type. Add property taxes and insurance separately to estimate the total monthly housing cost rather than stopping at principal and interest.
5. Principal and interest are not the whole payment
Many borrowers are surprised when their total monthly housing payment is higher than the calculator’s basic loan figure. That happens because the full payment can include several components:
- Principal: the part that reduces the balance you borrowed.
- Interest: the financing cost charged by the lender.
- Property tax: often collected monthly into an escrow account.
- Homeowners insurance: coverage for damage and liability.
- Mortgage insurance: possible on some low-down-payment loans.
- HOA or service charges: common in condominiums and planned communities.
Taxes and insurance vary by location and property. A calculator can show the arithmetic, but you should replace generic assumptions with current local estimates before making an offer.
6. How the down payment changes affordability
A larger down payment lowers the loan balance and usually reduces the required monthly payment. It can also reduce the amount of interest paid over time. But using every available dollar for the down payment is not always the best decision. Homeowners still need cash for closing costs, moving, repairs, furnishings, maintenance, and an emergency fund.
Compare at least three down-payment scenarios. For example, model 5%, 10%, and 20%. Look at the monthly payment, estimated mortgage insurance, upfront cash required, and the total interest over the life of the loan. The best choice is not automatically the largest down payment; it is the option that fits both your monthly budget and your cash-reserve needs.
7. 30-year versus 15-year mortgages
A 15-year mortgage normally requires a higher monthly payment because the balance must be repaid in half the time. In return, the total interest can be substantially lower. A 30-year loan lowers the required monthly payment and may leave more room for investing, childcare, repairs, or other goals.
Use the calculator to compare the same loan amount and interest rate under both terms. Focus on two outputs: the required monthly payment and the total interest. Then consider flexibility. A lower-payment loan may be easier to manage during a difficult year, while a shorter term can build equity faster if the payment remains comfortable.
8. Fixed-rate and adjustable-rate assumptions
The standard formula works cleanly for fixed-rate loans because the interest rate remains constant. Adjustable-rate mortgages need extra care. The initial rate may last for a set period and then change according to an index, margin, and adjustment caps. A calculator can estimate the introductory payment, but it cannot predict future rates with certainty.
If you are comparing an adjustable-rate loan, run several scenarios: the initial rate, a moderate increase, and a higher stress case. The goal is not to predict the future perfectly; it is to test whether the payment would still be manageable if the rate resets higher.
9. How extra payments affect the loan
Extra principal payments can reduce the balance faster and lower the interest charged in future months. Even a small recurring amount can shorten the repayment period. To evaluate the effect, compare a baseline mortgage with a second scenario that adds an extra amount each month or an annual lump sum.
Check your loan terms before making extra payments. Some products have prepayment rules, and not every borrower should prioritize mortgage repayment over higher-interest debt, retirement contributions, or maintaining an adequate cash reserve. A calculator helps quantify the trade-off so you can decide with clearer numbers.
10. Using a mortgage calculator for a realistic budget
Start with a payment you can sustain, not the maximum a lender may approve. Build a monthly housing budget that includes the estimated mortgage payment, utilities, maintenance, insurance, taxes, and recurring fees. Then test the budget against a higher-rate scenario, a temporary income reduction, or a large annual repair.
It also helps to work backward from a target payment. If you know the maximum monthly amount you want to spend, adjust the home price, down payment, term, and interest rate until the estimate fits. This approach can prevent you from shopping for properties that look affordable on the listing page but are uncomfortable after taxes, insurance, and maintenance are included.
11. Common mortgage calculator mistakes
- Using the home price as the loan amount without subtracting the down payment.
- Comparing loans with different terms but looking only at the monthly payment.
- Leaving property taxes and insurance at zero because the calculator allows it.
- Assuming the interest rate shown online is guaranteed for every borrower.
- Ignoring closing costs, prepaid escrow, repairs, and ongoing maintenance.
- Rounding too early when comparing close scenarios.
13. Frequently asked questions
What does a mortgage calculator estimate?expand_more
It estimates principal and interest and may include taxes, insurance, mortgage insurance, HOA dues, and other housing costs.
Is a lower monthly payment always better?expand_more
No. A lower payment can come from a longer term or a larger loan, both of which may increase total interest or financial risk.
How much should I budget beyond principal and interest?expand_more
There is no single universal amount. Use local tax and insurance estimates, then add maintenance, utilities, HOA dues, and a repair reserve.
Can I use the calculator before I know the exact interest rate?expand_more
Yes. Run a range of rates and focus on how the payment changes. This is often more useful than relying on one optimistic assumption.